To check tow car insurance coverage, open your current policy before arranging service. Find the roadside section, confirm who must order the tow, and ask your insurer what records it requires. Coverage isn’t automatic, and Quick Tow EP can’t determine whether your policy will pay.
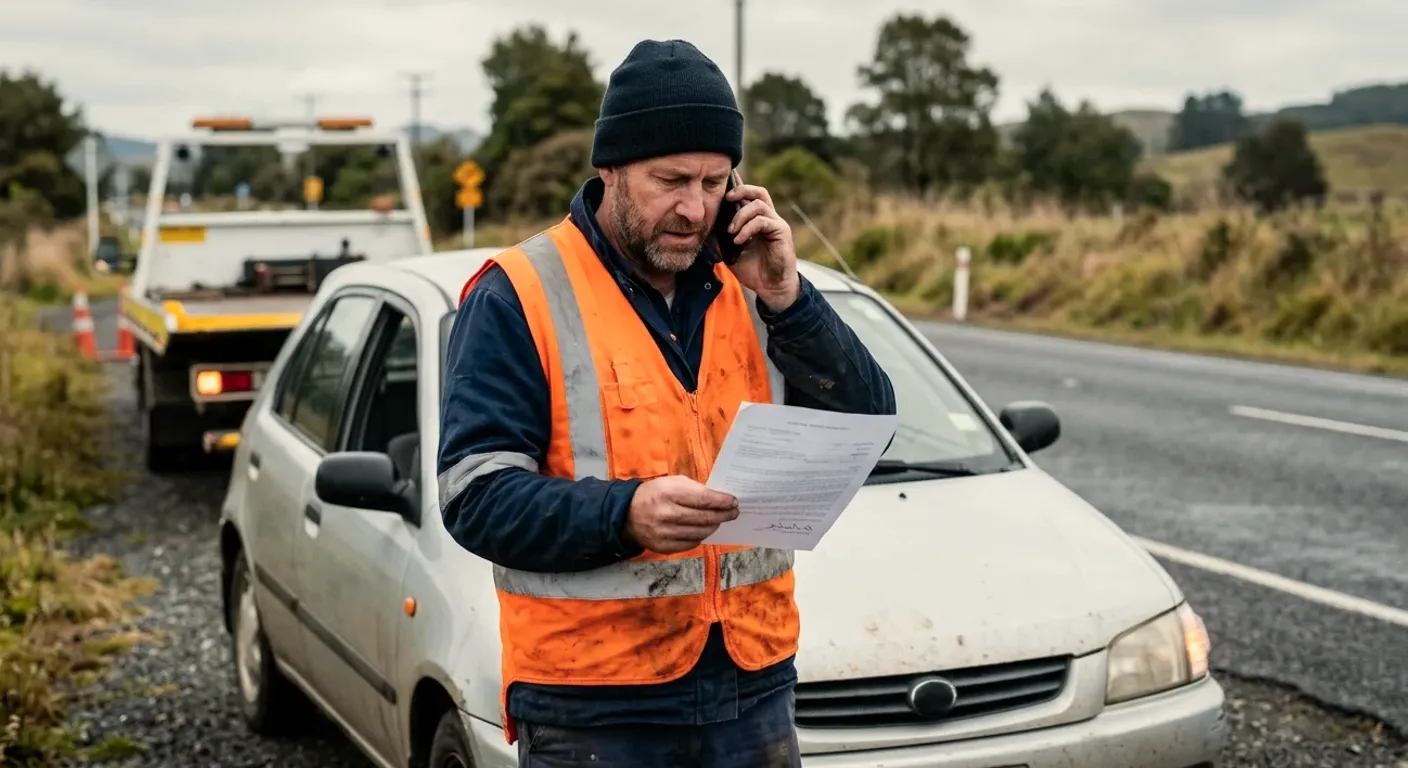
Find the roadside section of your policy
Start with the policy that’s active on the disabled vehicle. Check the insurer’s app, online account, declarations page, coverage documents, and any separate roadside plan.
Search those materials for terms such as:
- Towing
- Roadside assistance
- Emergency road service
- Transportation expenses
- Labor at the breakdown location
- Reimbursement
- Optional endorsements
Finding one of those phrases doesn’t confirm payment. Read the full section and any exclusions attached to it. The important language is the language in your current policy, not an old insurance card or a general description online.
Confirm that the listed vehicle matches the one needing service. If you’re driving a rental, borrowed car, work vehicle, trailer, or recently purchased vehicle, ask the insurer which document controls. Don’t assume the coverage follows you, the vehicle, or another household member.
Also check whether towing coverage appears as an optional item. If it isn’t clearly shown, contact the insurer before treating it as active. Ask the representative to point you to the exact policy section supporting the answer.
Save a screenshot or download the relevant page. Record the date and how you received the answer. If a later reimbursement question comes up, you’ll have the policy language you relied upon.
Quick Tow EP is a referral line, not an insurer. We can connect you with an independent, separately licensed local tow operator, but we can’t interpret your policy or approve insurance towing coverage.
Check who must arrange the tow
Next, determine whether your insurer must arrange the tow. Some policy language may instead describe reimbursement after the driver hires an operator. You need the rule stated in your own documents or confirmed by your insurer.
Ask these direct questions:
- Must the insurer arrange the towing service?
- Can I choose an independent towing company?
- Do I need authorization before the vehicle is hooked up?
- Is there a claim or authorization reference to record?
- If I pay the operator, can I request reimbursement?
- Which documents must I submit afterward?
Don’t let an insurance logo on an app or card answer those questions by implication. Get the arrangement rule from the current policy or the insurer.
If you call Quick Tow EP, explain whether the insurer has already authorized service. The driver deals with and pays the independent operator directly. Quick Tow EP doesn’t collect the payment, submit the claim, or guarantee reimbursement.
A driver-requested tow is a consent tow. The operator prices that work. Confirm the destination, equipment needs, and proposed price with the operator before the truck hooks up. Insurance coverage and the operator’s charge are separate questions.
Texas requires towing companies operating tow trucks over public roadways to be licensed. You can check a company or operator through the TDLR license search. That search verifies licensing information. It doesn’t tell you whether your insurance will cover the tow.
If you can’t reach the insurer, read the policy’s towing and reimbursement language closely. Don’t assume that arranging service yourself creates coverage. Keep every record so the insurer can review the request later.
Confirm any destination restrictions
Before choosing a shop, home, dealership, or storage location, check whether your policy limits the destination. Ask your insurer to identify any applicable language rather than relying on a general roadside description.
Use the actual starting point and intended destination. In El Paso, “nearby” can describe very different trips. A tow from the Westside under the Franklin Mountains isn’t the same route as one from the Lower Valley. Trips from I-10, Loop 375, US-54, Mesa Street, or Horizon Boulevard can also end in different jurisdictions.
Tell the insurer if the tow would cross the Texas and New Mexico line. Sunland Park and Santa Teresa are in New Mexico, while El Paso is in Texas. Texas towing rules don’t apply to a tow occurring in New Mexico. Don’t assume an insurance answer for an El Paso destination also covers a destination across the state line.
Ask the insurer:
- Is there a required type of destination?
- Must the destination be selected or approved in advance?
- Does the policy limit how far the vehicle may be taken?
- What happens if the first destination can’t accept the vehicle?
- Does crossing a state line change the approval process?
- Must the destination appear on the receipt?
No universal answer applies to every policy. If the representative gives instructions, write them down. Ask where those instructions appear in the policy or claim record.
Give the independent operator the exact destination before agreeing to service. Quick Tow EP doesn’t choose a repair facility or determine what your insurer will approve. If you haven’t selected a destination, say that when calling. It may affect what the operator needs to discuss with you before the tow begins.
Keep records from the independent operator
Good records give the insurer something concrete to review. Before service, ask your insurer what information its towing reimbursement request requires. Then ask the independent operator whether the needed details can appear on the receipt or other paperwork.
Record the operator’s company name and contact information. Note the pickup location, destination, service date, vehicle details, and reason for the tow. Keep any authorization or claim reference supplied by the insurer.
Ask what proof of payment the insurer accepts. Don’t assume a bank notification, handwritten note, or phone screenshot will meet its requirements. The insurer should identify the documents it needs.
Keep copies of:
- The relevant policy section
- Messages or instructions from the insurer
- Any authorization or claim reference
- Paperwork supplied by the operator
- Proof of payment accepted by the insurer
- Photos the insurer specifically requests
- The pickup and destination details
Don’t alter the operator’s paperwork. If something is missing, contact the operator and ask whether corrected or additional documentation is available. Quick Tow EP doesn’t create receipts for the operator or change its records.
El Paso drivers should also distinguish an insurance claim from an impound release. A vehicle taken after a police-ordered tow may involve the City of El Paso Municipal Vehicle Storage Facility. That is different from hiring an operator for a consent tow. The El Paso Police Department vehicle-towing page explains how to find and retrieve a city-towed vehicle.
For a regular roadside tow, keep the documents together until the insurer finishes reviewing the request. Coverage still depends on the policy and the insurer’s decision.
Ask the insurer about reimbursement
Towing reimbursement isn’t something Quick Tow EP or the independent operator can approve. Contact the insurer and ask how to submit the request under your current policy. Don’t rely on a process remembered from an older policy or another company.
Use specific questions:
- Does my current policy include towing reimbursement?
- Was prior authorization required in this situation?
- Where should I submit the request?
- Which documents are required?
- Is there a submission deadline stated in my policy?
- How will I know the request was received?
- What should I do if more information is requested?
Ask the insurer to confirm any deadline, limit, or destination rule from your policy. No reimbursement amount is universal, so don’t treat another driver’s result as evidence of what your plan will pay.
Submit only accurate records. Keep copies of everything sent and note the submission date. If the insurer requests more information, ask exactly what’s missing. If it denies the request, ask for the policy language and reason supporting that decision.
The towing operator’s payment remains separate from the insurance review. The driver deals with and pays the operator directly. A possible reimbursement request doesn’t change that arrangement unless the insurer and operator have specifically told you otherwise.
If you need roadside help without a membership, our roadside service referral page explains how the connection works. Calling Quick Tow EP doesn’t create insurance coverage or guarantee reimbursement. It connects you with an independent local operator so you can discuss the tow directly.
When to call us
Call when your vehicle needs a licensed towing pro and you’ve confirmed any insurance arrangement rules you can. Call us at (915) 615-5465 and we’ll connect you with an independent licensed operator who handles this work. If nobody picks up, leave a voicemail.